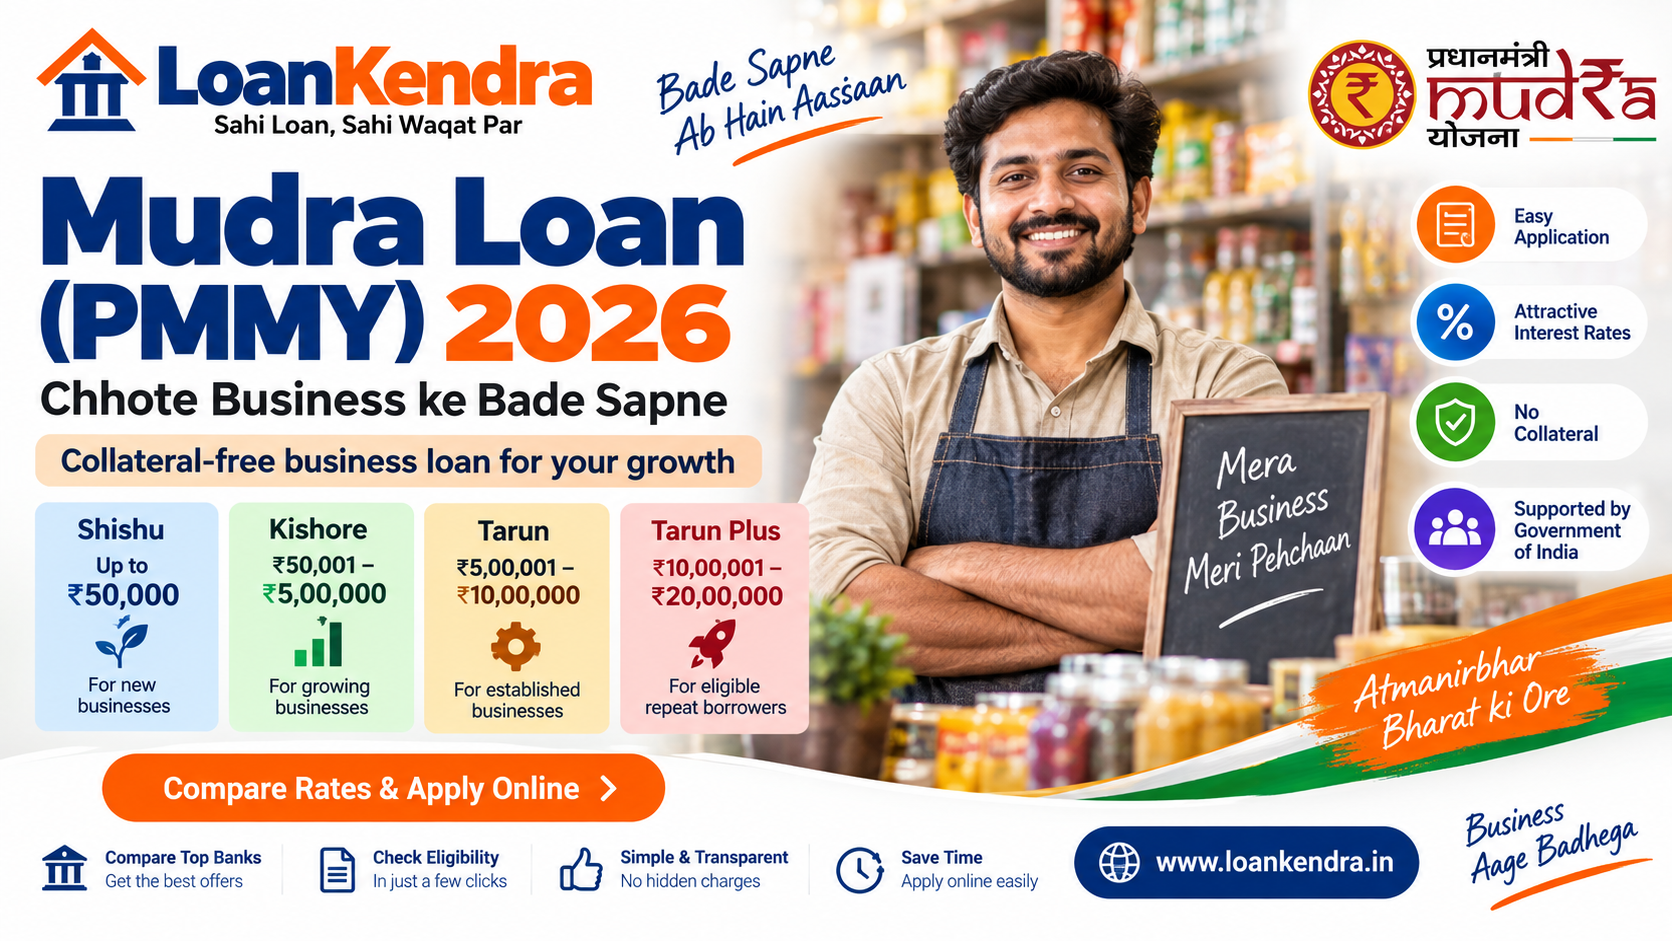
If you run a small retail shop, a manufacturing workshop, a food venture, or a local service business and need funding without pledging property collateral, the Pradhan Mantri Mudra Yojana (PMMY) — commonly known as a Mudra Loan — is one of the most accessible government-backed credit schemes in India.
However, most small business owners make a critical mistake: they walk into a single local bank branch, face paperwork objections or delayed branch queues, and give up. At LoanKendra, our objective is to provide complete transparency — helping you understand exact category limits, compare live interest rates across public and private banks, and prepare your paperwork so your file gets approved quickly.
Planning to Apply for a Mudra Loan in Bihar?
Get free eligibility pre-screening and doorstep documentation support across Darbhanga, Madhubani, Samastipur, and Patna.
What Is PMMY / Mudra Loan?
Launched by the Government of India in April 2015, the Pradhan Mantri Mudra Yojana (PMMY) was established to provide formal institutional credit to non-corporate, non-farm micro and small enterprises. Rather than lending directly to borrowers, the scheme is administered by MUDRA (Micro Units Development & Refinance Agency Ltd.), which acts as a refinancing agency channeling capital through:
- Public Sector Nationalized Banks (SBI, Bank of Baroda, PNB, Canara Bank, etc.)
- Private Sector Commercial Banks (HDFC, ICICI, Axis Bank)
- Regional Rural Banks (RRBs like Dakshin Bihar Gramin Bank & Uttar Bihar Gramin Bank)
- Small Finance Banks (SFBs) and Microfinance Institutions (MFIs)
- RBI-registered Non-Banking Financial Companies (NBFCs)
Originally, the Mudra loan scheme was capped at a strict ceiling of ₹10 lakh. Following recent Central Government budget notifications, a brand-new "Tarun Plus" category has been operationalized. This allows collateral-free credit up to ₹20 lakh for ambitious entrepreneurs who have previously availed and successfully repaid a Tarun loan.
*Note: Most older competitor websites — and even several single-bank portal pages that have not updated since 2024 — still state the maximum limit is ₹10 lakh. The ₹20 lakh Tarun Plus limit is active for eligible repeat borrowers.*
Mudra Loan Categories: Shishu, Kishore, Tarun & Tarun Plus
To accommodate businesses at different stages of maturity — from street vendors and home bakers to established workshops and distributors — PMMY divides funding into four distinct tiers:
| Category | Loan Amount | Best Suited For | Margin Money |
|---|---|---|---|
| Shishu | Up to ₹50,000 | New micro-units, roadside shops, artisans, fruit/vegetable vendors, tailoring units | 0% (Nil) |
| Kishore | ₹50,001 to ₹5,00,000 | Developing businesses purchasing equipment, stocking raw inventory, or renovating premises | Up to 15% – 20% |
| Tarun | ₹5,00,001 to ₹10,00,000 | Established enterprises adding heavy machinery, modernizing facilities, or hiring staff | Up to 15% – 20% |
| Tarun Plus (New) | ₹10,00,001 to ₹20,00,000 | Repeat entrepreneurs with a clean repayment history under Tarun scaling across districts | Up to 15% – 20% |
Who Can Apply? (Mudra Loan Eligibility Criteria)
One of the biggest advantages of the Mudra Loan scheme is its inclusivity. Traditional commercial business loans usually require 3 years of audited balance sheets and ₹50+ lakh annual turnover. In contrast, PMMY focuses on commercial viability and cash flow:
✔ Eligible Business Structures
Proprietorship firms, partnership businesses, small private companies, self-employed individuals, artisans, and commercial service operators.
✔ Covered Economic Sectors
Manufacturing units, retail trade, wholesale dealers, transport vehicles (taxis, e-rickshaws, small trucks), service clinics, beauty salons, and allied agricultural activities (dairy, poultry, pisciculture, bee-keeping).
✔ Zero Minimum Turnover Rule
There is no mandatory minimum revenue floor for Shishu loans, making it ideal for first-time entrepreneurs launching a startup unit.
✔ Age & Credit Standing
Indian citizens aged 18 to 65 years. While a CIBIL score of 680+ speeds up processing, clean daily banking transactions can qualify applicants with limited formal credit histories.
Interest Rates, Margin & Fees
Because MUDRA does not set a single fixed interest rate, each lending bank prices the loan based on its internal cost of funds, benchmark rates (such as EBLR or RLLR), and the applicant's risk evaluation:
- Interest Rate Range: Most leading public and private banks offer Mudra loans at interest rates between 8.50% and 12.00% p.a.
- Margin Money:
- Shishu (Up to ₹50,000): 0% margin (the lender funds 100% of the project cost).
- Kishore, Tarun & Tarun Plus: Usually 15% to 20% margin (the borrower invests this portion as equity contribution).
- Processing Fees: Under RBI guidelines, banks charge zero processing fee for Shishu and Kishore loans. For Tarun and Tarun Plus categories, banks may levy a nominal administrative fee of around 0.50% of the loan amount (+ GST).
Mudra Loan Interest Rate Comparison Across Top Banks (2026)
Lenders vary significantly in their processing speed, benchmark markups, and documentation scrutiny. Here is an up-to-date comparative analysis of major banks offering Mudra loans in India and Bihar:
| Lender / Bank | Indicative Interest Rate (p.a.) | Processing Fee | Max Loan Limit | Key Advantage |
|---|---|---|---|---|
| State Bank of India (SBI) | 8.65% – 11.15% | Shishu/Kishore: Nil Tarun: 0.50% |
Up to ₹20 Lakh | Extensive branch presence in Bihar & digital e-Mudra sanction for existing customers |
| Bank of Baroda (BoB) | 8.75% – 11.25% | Shishu: Nil Others: 0.50% |
Up to ₹20 Lakh | Special concessional rates for MSME manufacturing units and women entrepreneurs |
| Punjab National Bank (PNB) | 8.80% – 11.40% | Shishu: Nil Others: 0.50% |
Up to ₹20 Lakh | Strong semi-urban network across Darbhanga, Madhubani & Samastipur |
| Canara Bank | 8.70% – 11.35% | Shishu: Nil Tarun: 0.50% |
Up to ₹20 Lakh | Dedicated MSME Sulabh desks for accelerated documentation processing |
| HDFC Bank | 9.50% – 13.50% | 0.50% – 1.00% | Up to ₹10 Lakh | Quick disbursal for businesses with healthy digital UPI/POS cash inflows |
| ICICI Bank | 9.75% – 14.00% | 0.50% – 1.00% | Up to ₹10 Lakh | Paperless overdraft options for active current account holders |
*Interest rates are linked to external benchmark lending rates (EBLR/RLLR) and may change periodically based on RBI monetary policy. For a comprehensive overview of general lending rates in Bihar, review our Bihar loan interest rates guide.*
Documents Required for Mudra Loan
Having an organized paperwork docket prevents branch objections and slashes approval time. Keep the following documents ready before submitting your application:
Identity & Address Proof (KYC)
Aadhaar Card, PAN Card, Voter ID, Driving License, or Passport (ensure names and DOB match exactly across all documents).
Business Establishment Proof
Udyam Registration Certificate (MSME Aadhaar), Municipal Trade License, Shop & Establishment Act registration, or GST Certificate (if registered).
Banking Records
Last 6 to 12 months' bank account statements of your primary current account or operating savings account showing daily cash/UPI sales.
Financial Statements & ITR (For Loans Above ₹2 Lakh)
Last 1–2 years' Income Tax Returns (ITR) with computation of income, projected balance sheet, and estimated sales turnover for Kishore/Tarun applications.
Asset Quotations / Project Estimates
Proforma invoice or official price quotation from the supplier if the loan is intended for purchasing machinery, commercial vehicles, or fixtures.
Need a complete checklist for personal and business loans? Review our detailed Bihar loan documents checklist.
How to Apply for a Mudra Loan Online (Step-by-Step)
You can initiate your application through the official government portal or take advantage of LoanKendra's assisted doorstep processing:
- Step 1: Evaluate Your Funding Category: Decide whether your funding requirement falls under Shishu (up to ₹50k), Kishore (up to ₹5 lakh), Tarun (up to ₹10 lakh), or Tarun Plus (up to ₹20 lakh).
- Step 2: Compare Lenders: Compare interest rate spreads and turnaround times. Avoid applying blindly at multiple banks simultaneously, as multiple hard inquiries will hurt your credit score.
- Step 3: Compile Documents: Assemble your KYC, Udyam registration, 6 months' bank statements, and quotations.
- Step 4: Submit Online Application: You can submit directly through the Central Government's official credit portal: JanSamarth Portal (www.jansamarth.in). Register with your mobile number, select "Business Activity Loan", choose Pradhan Mantri Mudra Yojana, and upload your digital documents.
- Step 5: Track Application Status: Use your digital application reference number to track progress online. Once in-principle approval is granted, the partner bank conducts field verification and issues the sanction letter.
🏛️ Official Government Lending Portals:
You can also review official guidelines and statutory annual reports directly on the Official MUDRA Portal (mudra.org.in) and the Central Government's JanSamarth National Portal.
Why Apply Through LoanKendra Instead of Applying Blind?
While the JanSamarth portal is a great digital initiative, thousands of applications get stalled at the local branch verification stage because of missing documentation, mismatched addresses, or branches meeting their monthly micro-credit limits.
At LoanKendra.in, founder Govind Kumar and our dedicated field team solve this bottleneck:
Doorstep Verification
We visit your shop or residence in Darbhanga, Madhubani, Samastipur, or Patna to verify papers before submission.
Smart Bank Routing
We match your file to the specific bank with the fastest current sanction speed and lowest interest markup.
Zero Upfront Brokerage
We work directly as authorized Direct Selling Agents (DSA) — no hidden broker commissions or advance fees.
Frequently Asked Questions (FAQs)
What is the maximum Mudra loan amount?
Under the original Pradhan Mantri Mudra Yojana scheme, the maximum loan amount was ₹10 lakh under the Tarun category. Under the expanded 2024–2026 guidelines, a new "Tarun Plus" category allows collateral-free loans up to ₹20 lakh for eligible repeat borrowers who have successfully repaid previous Tarun loans.
Is collateral required for a Mudra loan?
No — Mudra loans are 100% collateral-free across all categories (Shishu, Kishore, Tarun, and Tarun Plus). Borrowers are not required to mortgage land, property, or fixed deposits. The loans are covered under the Credit Guarantee Fund for Micro Units (CGFMU) backed by the Government of India.
Can I apply for a Mudra loan without GST registration?
Yes. Small shopkeepers, artisans, and service providers whose annual turnover is below the mandatory GST threshold (₹40 lakh for trading/manufacturing, ₹20 lakh for services) do not require GST registration to apply for Shishu loans (up to ₹50,000) or Kishore loans. An Udyam MSME Aadhaar certificate or local trade license is sufficient.
How long does Mudra loan approval take?
Mudra loan processing time typically takes 3 to 7 working days for Shishu and Kishore loans when submitted digitally or through assisted platforms like LoanKendra. For higher amounts under Tarun and Tarun Plus (up to ₹20 lakh), approval generally takes 7 to 14 working days depending on document verification and bank internal credit committee approval.
Get Your Mudra Loan Approved with LoanKendra
Don't let paperwork rejections delay your business growth. Request our free doorstep consultation across Bihar today.
*Disclaimer: LoanKendra is an independent loan facilitation partner and Direct Selling Agent (DSA). Final loan sanction, interest rate, tenure, and credit approval remain solely at the discretion of the lending bank or NBFC in accordance with RBI norms and PMMY scheme parameters.*